What should we make of the recent interest rate rises?

What should we make of the recent interest rate rises? By Gladstone Financial Planners - BA Wealth

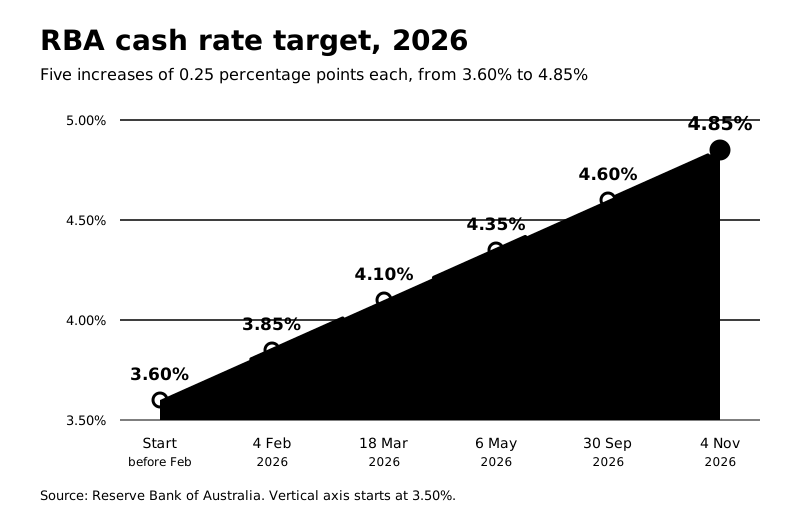
On Cup Day, 3 November, the Reserve Bank lifted the cash rate by 0.25 percentage points to 4.85 per cent. It’s the fifth rise this year, and the highest the rate has been since late 2008. If your stomach dropped a little when you read that, you’re in good company.
Australian interest rate rise animation

So what should we make of it? Honestly, there’s no tidy answer (and anyone who offers you one is probably guessing). There is a sensible way to think it through, though, and it starts with understanding what’s actually going on.

Where we’ve come from

The cash rate started the year at 3.60 per cent. Five increases of 0.25 percentage points later, it’s sitting at 4.85. That’s a climb of 1.25 percentage points in less than twelve months, which is a lot to absorb if you’ve got a loan.

The latest decision wasn’t unanimous either. Six members of the Reserve Bank’s Monetary Policy Board voted to lift the rate, while three wanted to hold. We find that split quite telling. Even the people making the call seem to be weighing it carefully.

Why the Reserve Bank is doing it

In a word, inflation. The Board describes it as elevated and broadly based, and says higher fuel and commodity prices linked to the Middle East conflict haven’t helped. Its latest forecasts have inflation staying above 3 per cent over the coming year, and not reaching the top of its 2 to 3 per cent target range until late 2027 – roughly three quarters later than it expected before.

Here’s where it gets uncomfortable. The economy is slowing. House prices have fallen significantly this year, and unemployment has risen to 4.7 per cent, with the Reserve Bank expecting it to climb further. Governor Michele Bullock has said the bank isn’t trying to tip the economy into recession if it can avoid it, but that inflation has to come down. Raising rates into a slowdown is a genuinely hard balancing act, and we don’t envy anyone doing it.

What it can mean at home

For anyone with a variable-rate home loan, the effect is fairly direct. Banks tend to pass rises on quickly. ABC reporting earlier this year estimated that each 0.25 percentage point adds roughly $91 a month to a $600,000 loan with 25 years to run. Stack five of those together and you’re somewhere near $450 a month (that’s our rough arithmetic, so please don’t treat it as gospel for your own loan).

If you’re on a fixed rate, nothing changes today. The catch is that when your fixed term ends, the loan usually rolls onto a variable rate, and the full effect of the rises arrives all at once. It’s worth knowing when that date is.

Savers are the other side of the coin. Savings and term deposit rates generally rise after a hike, so you may earn more on cash, provided your bank passes the increase on. And if you’re planning to buy, higher rates reduce how much lenders will let you borrow, which can quietly reshape your options.

What about investors and retirees?

It depends, as it so often does. Higher rates make investment debt more expensive to carry. In general, interest on money borrowed to invest may be tax-deductible, while interest on a home loan usually isn’t, which is why the structure of your debt matters as much as the size of it. For people living off the income from their assets, better returns on cash can help, but share and property values can move around too. None of this is simple, and it sounds a bit complicated because it is.

What happens next?

Nobody knows, and that’s not a cop-out. Economists are split. One has suggested another rise in February is his base case, while another expects the Reserve Bank to wait and see over summer. The bank itself says changes in the cash rate take 12 to 18 months to flow through the economy, so the full impact may not be clear until 2028.

We can’t control the weather, but we can check the roof. That’s really the point.

Questions worth asking yourself

We’re not going to hand out personal recommendations on a web page. Everyone’s situation is different, and that’s rather the point of sitting down together. What we can do is suggest some questions that tend to be useful.

Do you know exactly what your repayments are today, and what they’d look like another percentage point higher? When does your fixed term finish? Do you have an emergency fund that could carry you through a rough few months? Is your debt structured in a way that suits your goals, including the difference between deductible and non-deductible debt? And is your superannuation and investment strategy built for the long haul rather than this week’s headlines?

If a few of those made you pause, that’s useful information. It doesn’t mean something’s wrong. It just means a conversation might be worthwhile.

How we can help

Rate rises come and go, and we know everyone’s situation changes from time to time. A personalised Financial Advisory Masterplan is designed to keep working through all of it, whether that means looking at debt management, superannuation, protection for you and your family, or your plans for retirement.

Your first appointment is obligation-free. Our advice is fee-for-service, with fees agreed upfront based on the scope of advice you need. No surprises.

Start your financial journey with BA Wealth

You don’t need to have it all worked out. Start taking small steps today by booking in for an obligation-free, online appointment without leaving your home. Together, we’ll create a personalised plan to help you work toward lasting financial success!


The information provided in this article is general advice only. It does not take into account your personal objectives, financial situation or needs, and it is not personal advice. Before acting on any information, please consider whether it is appropriate for you and speak with an adviser. Examples are illustrative only and individual outcomes depend on your loan type, balance, remaining term and lender.

Where are you on the money map? How life stage shapes financial planning

Where are you on the money map? By Gladstone Financial Advisory Firm, BA Wealth

Ask ten people what “financial freedom” means and you’ll probably get ten different answers. One wants a first home. Another just wants the mortgage gone. A third is picturing a slow Tuesday morning with nowhere to be (we’ve heard all three, sometimes in the same week).

The thing is, what matters most to you tends to shift as life moves along. That’s why we like to think about planning in life stages rather than a single, one-size-fits-all checklist. Here’s how we see those stages, and what often sits at the centre of each.

Making a start

The early working years are, frankly, the most important step. There are usually no dependants yet, which can be a good moment to save hard and build habits that last.

For most people we meet at this stage, the focus is a first home deposit, getting on top of everyday money management, and working out how to make savings work harder. It doesn’t need to be big or dramatic. Small steps, repeated, seem to do more than one heroic effort.

Taking on more responsibilities and growing wealth

Careers build, finances settle a little, and then life piles on. A home loan, children, school fees, family holidays. Debt becomes a regular part of the picture. It can feel like a grind, and honestly, it is one at times.

This is often where we talk about paying down the family home loan, planning for children’s education, protecting your family with the right insurance cover, and understanding how investment debt can be managed in a tax-effective way. It’s also where growing wealth across a range of assets starts to feel realistic rather than abstract.

Learning how to make the most of a debt-free life

Then something quietly wonderful happens. The home loan is gone, work feels secure, and the family isn’t leaning on you quite as heavily. So what’s next?

Plenty of people we work with ask exactly that. Some choose to take on investment debt and build wealth more actively, while others focus on increasing their tax savings. There’s no single right answer here (and we’d be wary of anyone who says there is). It depends on you, your goals, and how you feel about risk.

Keeping an eye on retirement

You can see the finish line now. It’s close enough to picture, and far enough away that decisions still count.

At this stage the conversation often turns from growing wealth to protecting it. That might mean holding a diversified mix of assets, paying off any remaining investment debt, and mapping out the travel you’ve been promising yourself for years. Retirement is a marathon, not a sprint – and the final stretch is where pacing matters most.

Enjoying retirement

Here’s something we’ve noticed: retirement isn’t tied to a particular age. Plenty of our clients still enjoy working, and that’s absolutely fine. The point is that you choose how you want to live.

Planning at this stage often centres on relying on the income from assets you’ve built over a working life, passing wealth on in a tax-efficient way, and supporting children and grandchildren. Travel and protecting what you’ve built stay on the list, too.

Areas where we can help

Life stages overlap, of course, and no two clients look quite the same. So it helps to know the full range of topics we can talk through with you:

  • Building wealth, including investment properties and investment portfolios
  • Debt management, such as consolidation, deductible versus non-deductible debt, and debt recycling
  • Superannuation, including consolidation, contributions and investment strategies
  • Retirement planning, from income streams to tax strategies
  • Protection for you and your family, from emergency funds to cover for death, injury, trauma or loss of income
  • Centrelink, including the Age Pension and the assets and income tests
  • Taxation, from income tax to small business CGT concessions
  • Estate planning, covering wills, beneficiaries and power of attorney

We’re not going to hand out personal recommendations on a web page. Everyone’s situation is different, and that’s rather the point of sitting down together.

How your Masterplan experience works

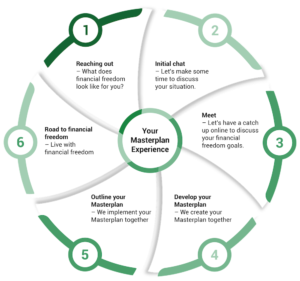
Our process is simple on purpose. It starts when you reach out, followed by an initial chat so we can understand what you’re hoping to achieve. Then we meet, either online or in person, and develop your personalised Masterplan. Once it’s ready, we outline it with you step by step, so you know exactly what it means and what comes next. From there, it’s the road to financial freedom.

Your first appointment is obligation-free. Our advice is fee-for-service, and fees are agreed upfront based on the scope of advice you need. No surprises.

It’s also worth saying that your situation will probably change along the way. We know everyone’s does from time to time, and a plan should be able to move with you.

Start your financial journey with BA Wealth

Wherever you sit on the map right now, there’s a sensible next step. You could start taking small steps today by booking in for an obligation-free, online appointment without leaving your home. Together, we’ll create a personalised plan to help you work toward lasting financial success!


General advice only. The information in this post is general in nature and does not take into account your personal objectives, financial situation or needs, so it is not personal advice. Fees are fee-for-service and agreed upfront based on the scope of the advice.

BA Wealth opens in South Gladstone

Brent and Adam standing next to welcome to Gladstone sign

Our Gladstone Financial Planning office is open

We are delighted to share that BA Wealth has officially started providing financial planning in Gladstone. Our new office at Suite 4, 1 Manning Street, South Gladstone, is ready to welcome you, and we’re excited about the way everything has worked out!  Opening an office is a big step for any firm, and we have taken it because we want to be closer to the people we serve.

Our clients across the region have already shown us how much they value personal, planned advice. Having a local base means we can give that even more. Whether you are just starting out, growing your wealth, working toward a debt-free life or planning for retirement, we are here to help you take the next step.

Good news like this is worth celebrating, and we want to celebrate it with you. Book a time to talk, or simply get in touch to say hello. We would love to meet you.

Why we chose this location in Gladstone

Manning Street sits an easy few minutes from the middle of Gladstone. It is a quieter, residential part of town, and it is still central for clients across the wider region. We like it that way. A calm setting makes it easier to talk through the things that really matter to you, from your income and savings to the goals you have for the years ahead.

The suburb has an established community, and Toolooa State High School and Trinity College are just up the way. That sense of community matters to us, because the planning we do is personal. It works best when we understand the life you are building, and the people around you.

Clients from Boyne Island, Tannum Sands, Calliope and beyond can reach us with ease. Our location is central for the whole region, not just one suburb, and we want every client to feel that the drive is worth it. Whether you come in person or meet with us online, the aim is the same: a conversation that leaves you clearer about your next step.

Gladstone, and the people who live and work here

Brent Raverty and Adam Vermillion from BA Wealth discussing financial planning strategy in their Gladstone officeGladstone is a Central Queensland harbour city of more than 45,000 people. It is a working town and a genuinely beautiful one, side by side. The port, LNG plants, aluminium smelting and alumina refining, and power generation form the economic base of the city. That combination is really the whole story of the place.

The working side of Gladstone shapes how people earn. Shift work, overtime and project-based roles are part of everyday life for many families here, and redundancies and changing roles happen too. These income patterns do not fit a one-size-fits-all approach. Our professional financial advice for Gladstone residents needs to fit how you actually earn and spend, and it needs to allow for the good years and the lean ones.

The lifestyle side is just as important. East Shores and the Gladstone Marina, Lake Awoonga, Tondoon Botanic Gardens, Curtis Island and the harbour lookouts give locals plenty of places to unwind. Gladstone is also a gateway to the Southern Great Barrier Reef, with Heron Island, Lady Musgrave Island and Wilson Island among the destinations people reach from here. Agnes Water, the Town of 1770 and Kroombit Tops National Park are within reach too.

That mix of work and lifestyle is why we see Gladstone as the right place for a planning practice. People here work hard, and they deserve advice that respects both their careers and their time off.

How we work with you

Every client’s situation is distinct, so we start by getting to know yours. Our approach is built around a personalised Masterplan, a clear roadmap that sets out where you are today, where you want to be and the steps to get there. Financial freedom is rarely a single decision. It comes from patience, discipline and a plan that is reviewed as life changes.

We work with you to identify the factors that matter most to your financial success, help you overcome the obstacles in your way, and support you in making sound decisions along the way. We know everyone’s situation changes from time to time, so we build in the flexibility to adjust and adapt as your life moves on.

Our advice is delivered on a fee-for-service basis. Fees are agreed upfront and based on the scope of the advice you need, so you know what to expect before we begin. Your first appointment is an obligation-free discussion of your goals, and it can be in person or online.

Our planning covers every stage of life: making a start, taking on more responsibilities and growing wealth, working toward a debt-free life, focusing on retirement and enjoying retirement. Wherever you are on that path, we can help you map the next step.

Come and see us

Our office is at Suite 4, 1 Manning Street, South Gladstone. Visits are by appointment, so please book by phone or email and we will arrange a time that suits you. If getting to the office is not convenient, you can meet with us online instead.

Our principal advisers, Brent Raverty and Adam Vermillion, are looking forward to meeting the Gladstone community. Brent has worked in banking and finance since 2008, and Adam brings varied industry experience and a focus on client partnership to every conversation. Both are committed to helping you build a plan that reflects your life, not a generic template.

Whether you are a long-time local or new to the region, we would love to hear from you. Bring your questions, or simply bring your goals, and we will take it from there.

Start your financial journey in Gladstone

Your financial freedom is a marathon, not a sprint, and your Masterplan is the first step. Start taking small steps today by booking an obligation-free appointment, in person or online, without leaving your home if that suits you.

Together, we’ll create a personalised plan to help you achieve lasting financial success. We are proud to be part of Gladstone, and we look forward to getting to know you!

General advice only. The information in this post is general in nature and does not take into account your personal objectives, financial situation or needs, so it is not personal advice. Fees are fee-for-service and agreed upfront based on the scope of the advice.